When Does Return to Invoice Become Useful in a Car Insurance Claim?
A return to invoice becomes relevant when a serious loss leaves a car owner facing a gap between the vehicle’s current insured value and what was originally paid. This add-on is mainly designed for situations where the car is stolen or damaged beyond practical repair.
It can make a major claim easier to manage by bringing the settlement closer to the applicable invoice value. The exact benefit, however, depends on the policy wording, vehicle eligibility and the circumstances of the claim.
For a Total Loss
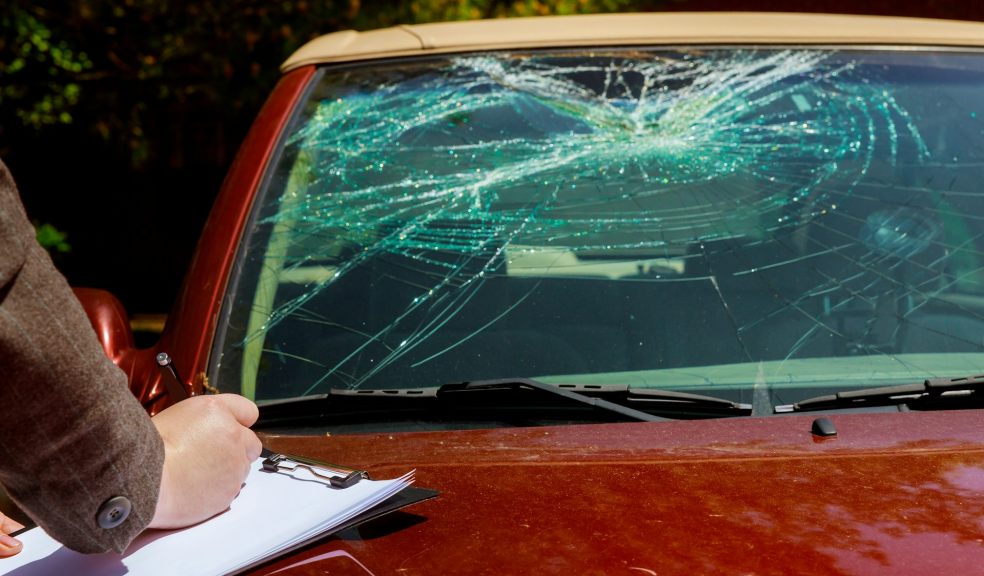
A severe accident can sometimes damage a vehicle to the point where repairs are no longer practical. When the vehicle is declared a total loss, the claim amount under car insurance is generally linked to its insured declared value. Return to Invoice can be useful in such situations because it may help cover the difference between the depreciated value and the invoice value, subject to the add-on terms.
Keep in mind:
- The vehicle must meet the policy’s total-loss conditions.
- The claim remains subject to policy terms.
- The payable amount depends on the RTI wording.
For Car Theft
Losing a vehicle can create a larger financial concern than replacing individual parts. When an insured car is stolen, and the claim qualifies under the policy conditions, Return to Invoice can help reduce the gap between the insured declared value and the eligible invoice amount. This can make arranging a replacement easier.
It may help when:
- The theft claim is accepted under the policy.
- The vehicle meets the required claim conditions.
- RTI eligibility remains active at the time of loss.
When IDV Is Lower than the Invoice Value
Insured Declared Value reflects the value used for certain major own-damage claims and usually changes as depreciation applies. The original invoice value relates to the vehicle’s purchase value. When the difference between these values becomes meaningful, RTI can provide an additional financial cushion in an eligible total-loss or theft claim.
This matters because:
- Depreciation can reduce the insured value over time.
- A lower IDV can create a replacement funding gap.
- RTI may help bridge that gap, subject to policy terms.
For New Cars
A new car often represents an expense and an important part of mobility. During the earlier ownership period, the insured value may differ from the amount shown on the original invoice. Return to invoice can therefore be relevant for eligible newer vehicles, as losing the car entirely could create a financial gap.
It may be worth reviewing when:
- The car meets the insurer’s RTI eligibility criteria.
- Preserving purchase-value protection matters to you.
- Replacing the car would otherwise require extra funds.
To Cover Depreciation Loss
Depreciation changes what a vehicle is worth for insurance purposes, even when it is maintained. That difference may matter less during an ordinary repair claim, but it can become important when the vehicle is stolen or declared a total loss. RTI is designed for this value gap rather than routine repair expenses.
Its role is to:
- Reduce the effect of depreciation in eligible major claims.
- Bring settlement closer to the applicable invoice basis.
- Support replacement planning after a qualifying loss.
To Reduce Out-of-Pocket Costs
A total loss can leave the owner with more than the inconvenience of losing a car. There may be a difference between the claim amount based on insured value and the money needed to purchase another vehicle. Return-to-invoice can help limit that difference when the claim and vehicle meet policy conditions.
This may reduce the need to:
- Use personal savings for the value gap.
- Delay replacement because of a lower settlement.
- Rework household spending after a major loss.
For High-Value Cars
The financial gap created by depreciation can feel more significant when the vehicle carries a higher purchase value. For such cars, the difference between the applicable IDV and invoice value may become important when evaluating add-ons. RTI can offer support where a qualifying theft or total-loss claim would otherwise leave a sizeable replacement gap for the owner.
Consider:
- The current IDV is compared with the invoice value.
- Your ability to absorb the difference personally.
- The policy’s RTI eligibility and settlement basis.
When the Extra Premium Is Worth It
Return to invoice adds to the policy premium, so it should fit a need rather than be selected because it is available. It may make sense when the gap between IDV and invoice value would be difficult to manage after a claim. The decision should reflect car age, value, eligibility and your preferences.
Before choosing it, assess:
- The value gap you may need to fund.
- How important vehicle replacement is to you.
- The benefits stated in the policy wording.
Conclusion
A return to invoice is most useful when a car is stolen or damaged beyond practical repair, and the insured value may leave a gap against the original purchase value. Its purpose is to reduce that gap during an eligible major claim, rather than help with everyday repairs. It can be relevant for newer or higher-value cars, but suitability varies between owners. Reading the policy wording carefully helps ensure the add-on matches the vehicle, expected claim support and your overall financial comfort.